BUDGET & MONEY-SAVING PRACTICAL GUIDE
A practical visual guide to planning income, spending, and savings. Learn how to track expenses, manage bills, and build a realistic plan with practical examples.
Managing money can be challenging when monthly bills and unexpected expenses add up. A monthly budget helps you understand your spending, manage your income, and plan ahead. Understanding why you need a plan is the first step in learning how to create a monthly budget that fits your real life.
You don’t need a high income or complicated tools to get started. Learning how to create a monthly budget can help you control expenses, prepare for bills, and achieve your financial goals without giving up the things you enjoy.
In this article, you’ll learn:
- Why a monthly budget is important
- Step-by-step instructions to create your budget
- How to choose the right budgeting method
- Common mistakes to avoid
- Tips to stay consistent
- Helpful links and resources
Why a Monthly Budget Matters
A monthly budget helps you organize your income and allocate it between expenses, savings, and debt payments, giving you a clearer picture of your financial situation.
Key benefits of a monthly budget:
- Control spending: Understand where your money goes and set priorities.
- Save regularly: Set aside money for emergencies and future goals.
- Plan expenses: Prepare for upcoming bills and costs.
- Repay debt: Manage payments while covering essential needs.
- Achieve financial goals: Save for important purchases or travel.
Helpful Budgeting Resources and Tools
Reliable information can make financial planning easier. The following resources offer additional guidance.
Consumer Financial Protection Bureau Explore budgeting information and practical resources for managing money.
USA.gov: Managing Your Money Find official government information that can help you navigate personal financial matters.
FDIC: Money Smart Access financial education resources designed to help people make informed money decisions.
You can also use these free tools on AffordablyUSA to put your plan into practice:
Monthly Budget Calculator Organize your income, needs, wants, and savings.
Savings Goal Calculator Estimate how much to save regularly to reach a target.
Grocery Budget Calculator Plan food spending based on your household and shopping habits.
For more practical guidance, explore these related articles in the AffordablyUSA Budget & Money-Saving section:
How Much Should You Spend on Groceries Per Month?
How to Build an Emergency Fund on a Low Income
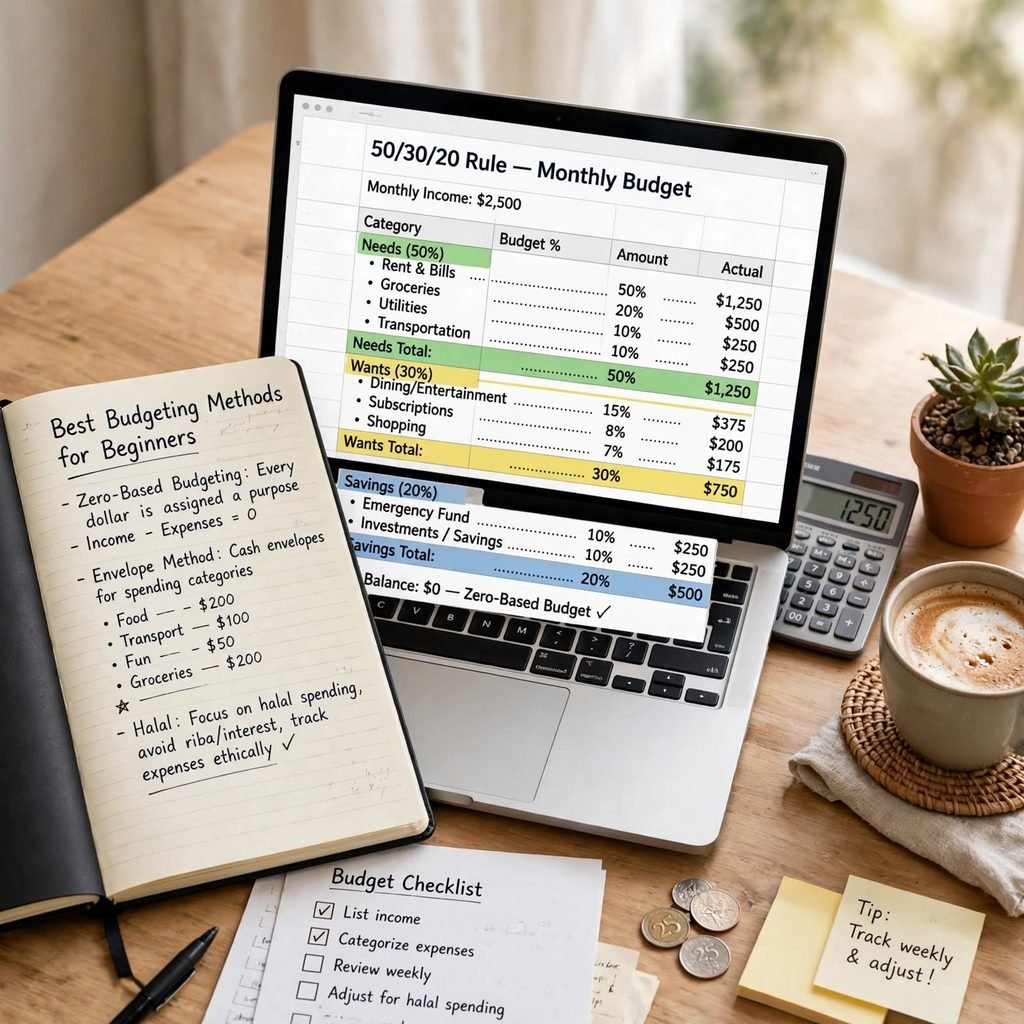
Best Budgeting Methods for Beginners: 50/30/20, Zero-Based, and More
How to Cut Monthly Expenses Without Sacrificing Essentials
The 50/30/20 Rule: A Simple Budgeting Framework
Many beginners find the 50/30/20 rule is the easiest way to learn how to create a monthly budget without feeling overwhelmed. The 50/30/20 rule divides your after-tax income into three categories: needs, wants, and savings or debt repayment.
- Housing
- utilities
- groceries
- transportation
- insurance
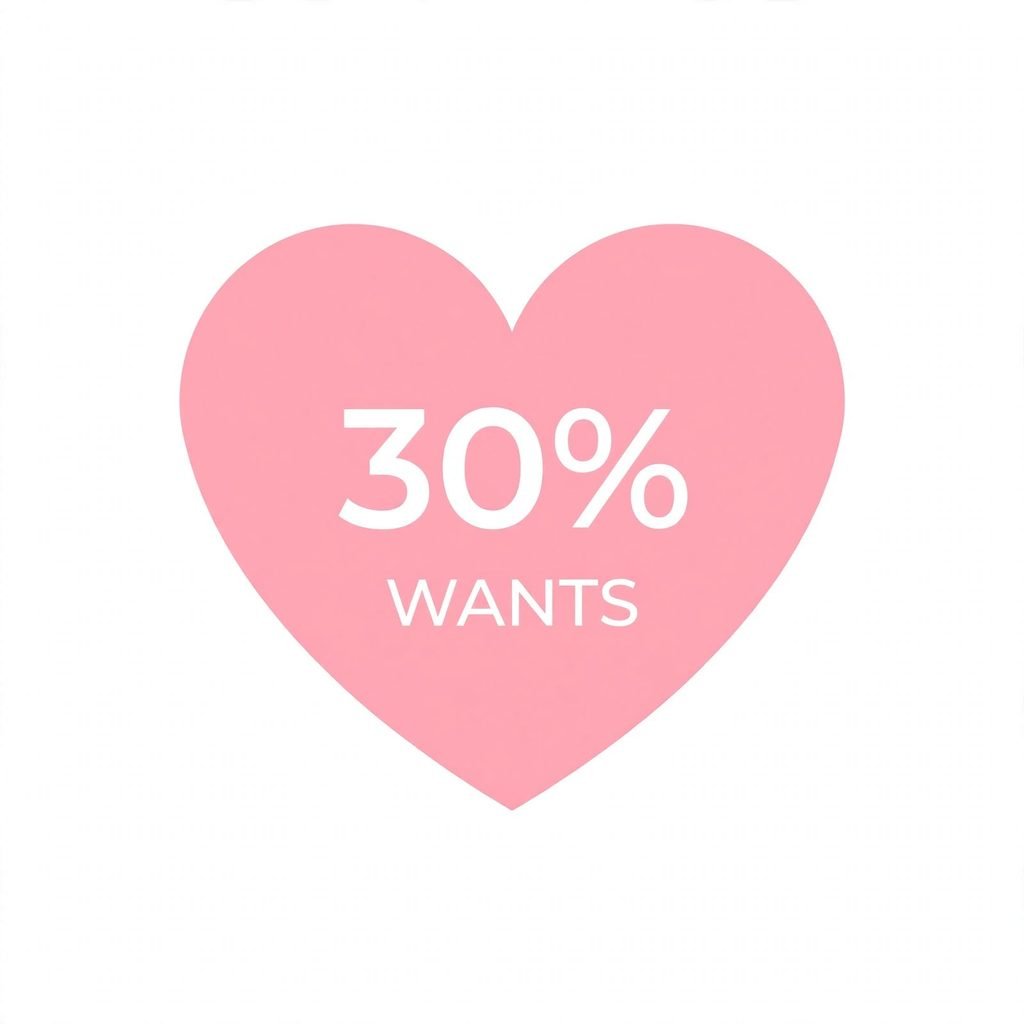
- Dining out
- entertainment
- hobbies
- travel
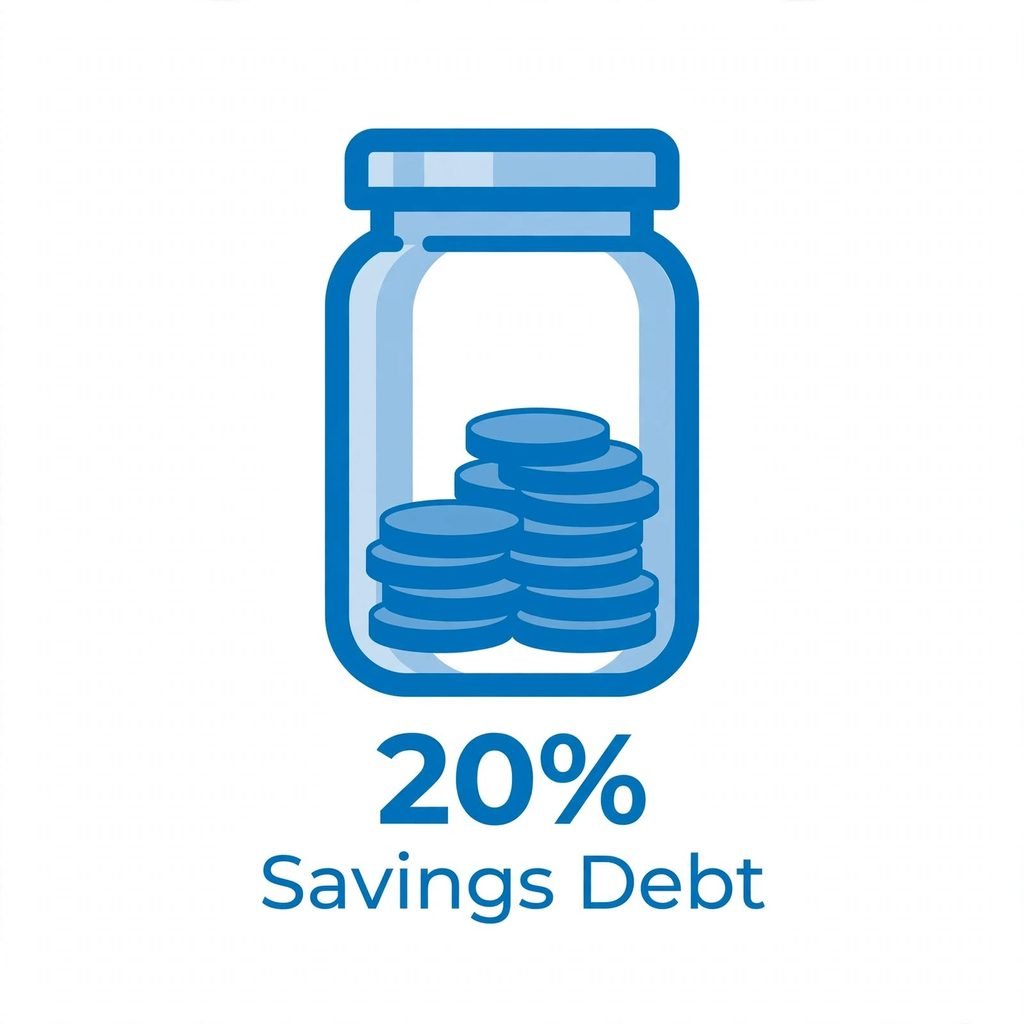
- Emergency fund
- retirement
- debt repayment
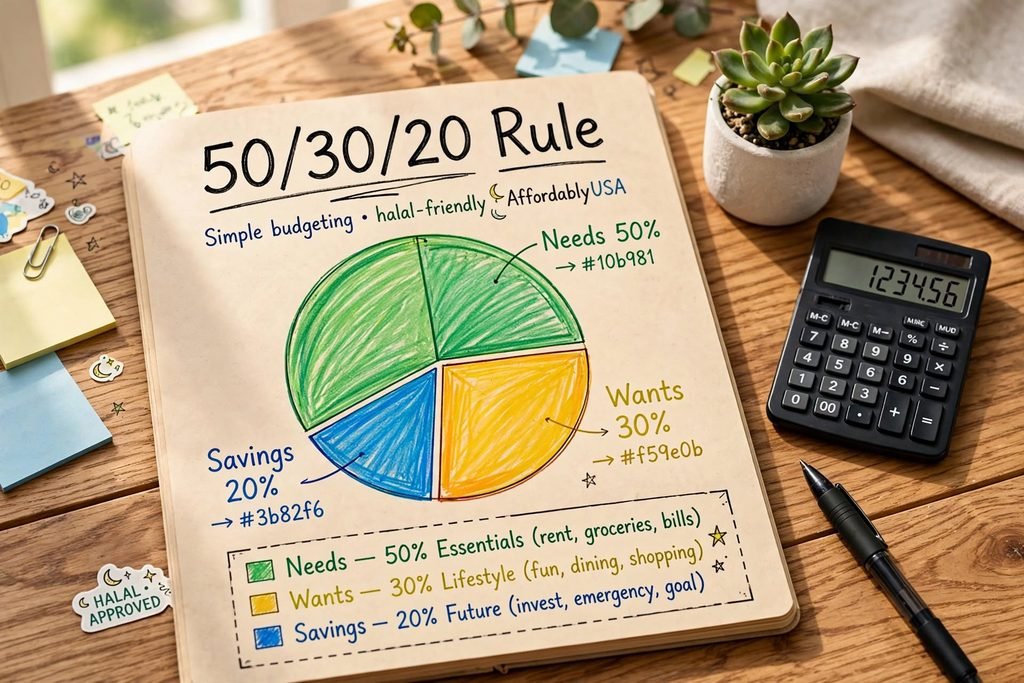
You can adjust these percentages based on your lifestyle and goals. For example, if you’re paying off high-interest debt, you might allocate more than 20% to debt repayment.
How to Create a Monthly Budget in Seven Steps
Creating a monthly budget does not have to be complicated. By reviewing your income and expenses, you can build a realistic spending plan that helps you manage your money and reach your financial goals.
Step 1: Calculate Your Monthly Take-Home Income
When you learn how to create a monthly budget, start by calculating the money you receive after taxes and other payroll deductions. Include your salary, reliable freelance earnings, side income, and other regular sources. If your income varies, use a conservative estimate based on your recent earnings. Your budget should reflect the money you can realistically count on.
Step 2: List Your Fixed Expenses
Write down your regular monthly bills, such as:
- Rent or mortgage payments
- Insurance, phone, and internet bills
- Car payments and minimum debt payments
- Childcare and other essential expenses
Remember to include annual or quarterly bills. For example, setting aside $50 each month for a $600 annual insurance payment can help you prepare in advance.
Step 3: Estimate Your Variable Expenses
Variable expenses include groceries, transportation, utilities, household supplies, and entertainment.
Review your spending over the past two or three months to estimate realistic amounts. For example, if you spent $420, $460, and $440 on groceries, your monthly average was $440.
Use your actual spending habits rather than setting limits that are difficult to maintain. The Grocery Budget Calculator can help you plan your food expenses.
Step 4: Set Savings and Debt Repayment Goals
Include savings and debt payments in your budget. Start with one or two priorities, such as building an emergency fund, paying off credit card debt, or saving for a major purchase.
For example, saving $1,200 over 12 months requires approximately $100 per month, assuming no interest or investment returns.
Use the Savings Goal Calculator to estimate how much you need to save each week or month.
Step 5: Choose a Budgeting Method
As you learn how to create a monthly budget, choose a method that fits your financial situation and is easy to maintain.
- 50/30/20 method: Allocate your income to needs, wants, and savings or debt repayment.
- Zero-based budgeting: Give every dollar a purpose, including bills, savings, and debt payments.
- Envelope method: Set spending limits for categories such as groceries, dining out, and entertainment.
Start with a simple approach and adjust it as your needs change. Consistency matters more than complexity.
Step 6: Compare Income With Expenses
Add up your planned expenses, savings, and debt payments, then compare the total with your monthly take-home income.
For example, a household earning $3,500 per month might plan the following budget:
| Budget Item | Monthly Amount |
|---|---|
| Housing and utilities | $1,250 |
| Groceries and household supplies | $450 |
| Transportation | $350 |
| Insurance and healthcare | $250 |
| Phone and internet | $100 |
| Minimum debt payments | $200 |
| Personal spending | $250 |
| Savings | $300 |
| Irregular expenses | $150 |
| Total planned allocation | $3,300 |
| Remaining amount | $200 |
The remaining $200 can provide a financial cushion or help you reach your savings goals. If expenses exceed income, review your spending and identify realistic adjustments.
The Monthly Budget Calculator can help you organize your income and planned expenses.
Step 7: Review and Adjust Your Budget
Review your spending regularly to see whether your plan is working. Compare actual expenses with your budget, check your savings progress, and identify unexpected costs.
At the end of each month, consider what went well and what needs to change. If your grocery expenses consistently exceed your estimate, adjust your budget rather than setting an unrealistic limit.
The key is to create a realistic plan, track your spending, and make adjustments as your financial situation changes.
Common Budgeting Mistakes to Avoid
Even a well-organized budget can fail if it does not reflect real spending patterns. Knowing these pitfalls will help you learn how to create a monthly budget that actually lasts more than one month.Watch out for these common mistakes.
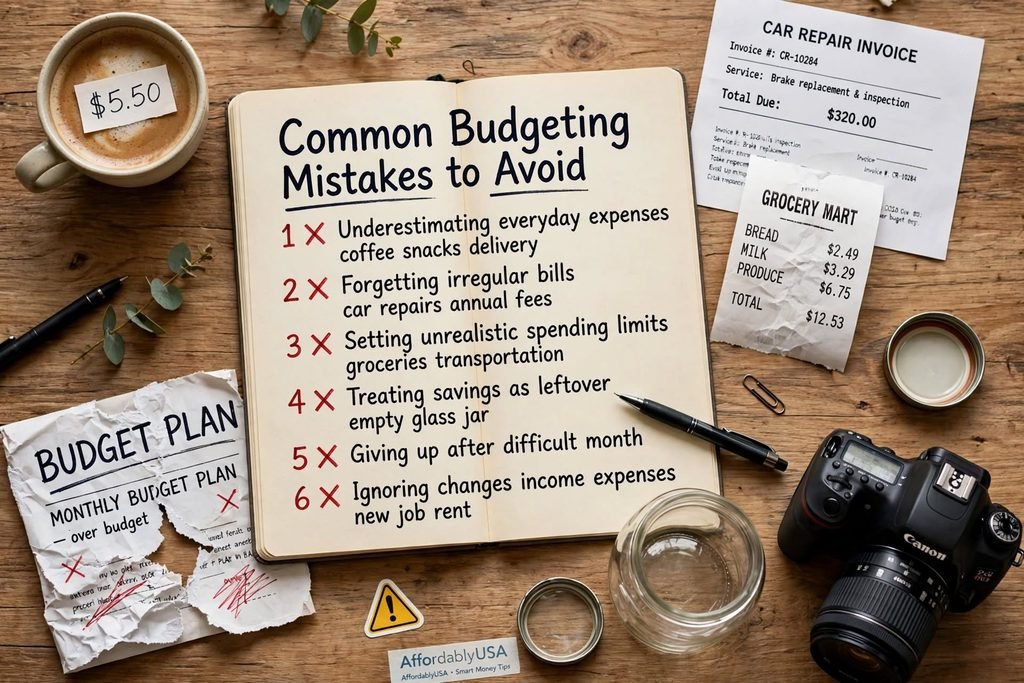
The most useful approach to how to create a monthly budget is to build a flexible system that can respond to real life without losing sight of your priorities.
Tips to Help You Stick to Your Budget
Creating a budget is only the beginning. Developing habits that make it easier to follow after you learn how to create a monthly budget is equally important.
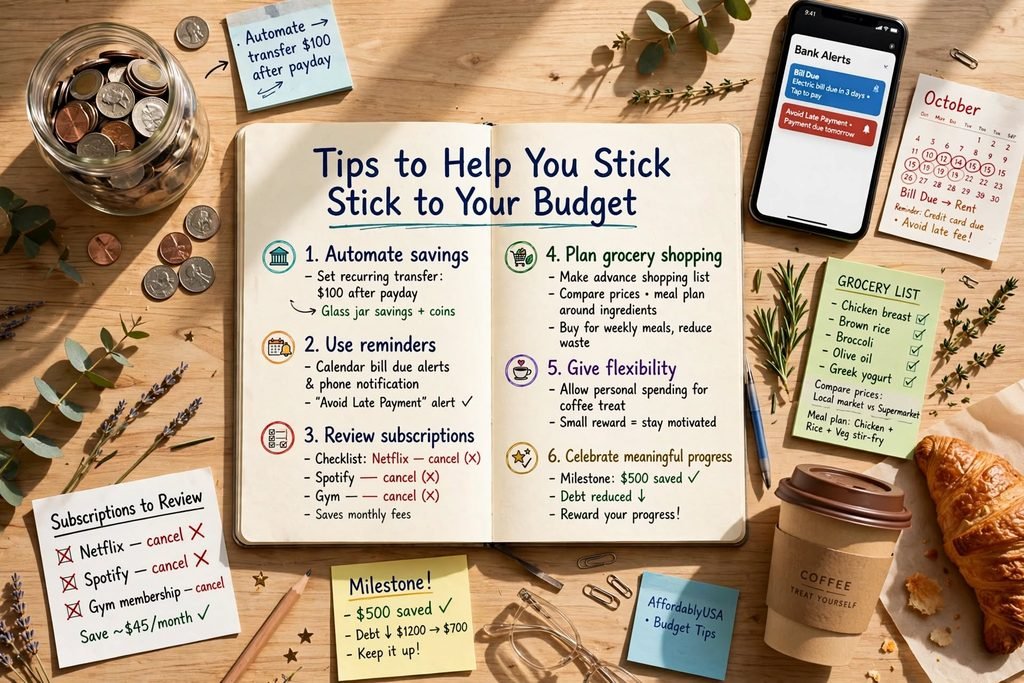
You do not have to make every decision perfectly. Small, repeatable improvements can gradually strengthen your financial position.
Final Thoughts
A budget does not need to be complicated to make a meaningful difference. By understanding your income, planning for expenses, setting achievable goals, and reviewing your progress regularly, you can make more deliberate decisions about your money.
The best approach to how to create a monthly budget is one that reflects your real circumstances and remains flexible when life changes. Start with a simple plan, learn from your spending patterns, and make improvements one month at a time.
Ready to put your plan into action? Use the Monthly Budget Calculator to organize your income and expenses, the Savings Goal Calculator to plan future savings, and the Grocery Budget Calculator to manage one of your most common household expenses.
Small, consistent steps can help you build better money habits and move toward a more secure financial future.
Frequently Asked Questions
Start by calculating your take-home income, listing fixed and variable expenses, and choosing a savings goal. Compare your planned spending with your income, then review the results each week. A simple spreadsheet or budgeting calculator can help you organize the numbers.
The 50/30/20 rule suggests allocating 50% of take-home income to needs, 30% to wants, and 20% to savings and debt repayment. These percentages are guidelines rather than strict requirements. Adjust them to reflect your housing costs, obligations, and financial priorities.
The right amount depends on your income, essential expenses, debt, and goals. The 20% savings target in the 50/30/20 rule is a useful starting point, but it may not be realistic for every household. Begin with an amount you can afford consistently and increase it when your circumstances allow.
First, identify the difference between your income and expenses. Review discretionary purchases, subscriptions, and bills that may be reduced. Consider whether you can increase your income or access assistance for essential needs. Avoid ignoring the shortfall, because unpaid bills and high-interest borrowing can make the situation more difficult.
The answer depends on your circumstances. Maintaining essential expenses and required debt payments is important. Building a modest emergency reserve can help prevent new borrowing when an unexpected bill arrives, while prioritizing expensive debt can reduce interest costs. Consider your interest rates, available cash, and immediate needs before choosing an approach.
Check your spending at least once a week and complete a more thorough review at the end of each month. Review your plan whenever your income, housing costs, debt payments, or family responsibilities change significantly.
Yes. Estimate income conservatively using recent earnings, prioritize essential expenses, and avoid committing uncertain income to fixed spending. During higher-income months, consider setting money aside to help cover lower-income months. Review your plan regularly as new income becomes available.
No. You can manage a budget using a spreadsheet, a notebook, or a simple calculator. Budgeting apps may automate tracking, but the most important elements are accurate records, realistic spending limits, and regular reviews. Choose a method that you can maintain comfortably.
Write down your monthly take-home income, list your essential bills, estimate your variable expenses, and choose one financial goal. Assign your available money to those categories, then compare your plan with your actual spending during the next week. Improve the plan as you learn more about your habits.