The best budgeting methods for beginners make managing money easier, especially if you are just getting started. Some methods use simple percentages, while others help you track every dollar or control spending in specific categories.
The best budgeting methods for beginners are not necessarily the most detailed ones. It is the one that fits your income, expenses, and daily habits.
In this guide, you will learn how popular budgeting methods work, their main advantages and disadvantages, and how to choose an approach that suits your financial situation.
The 50/30/20 Budget Rule
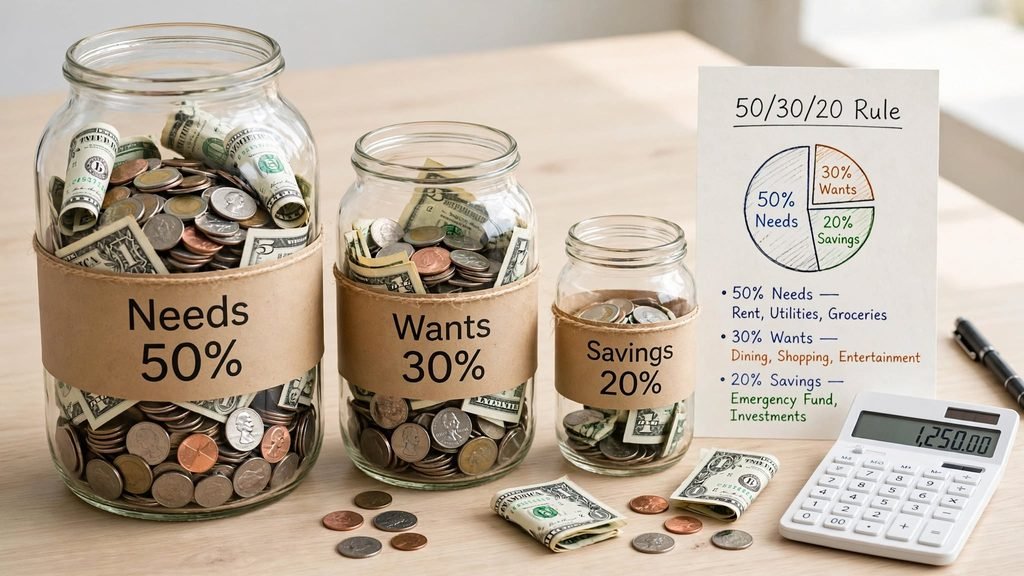
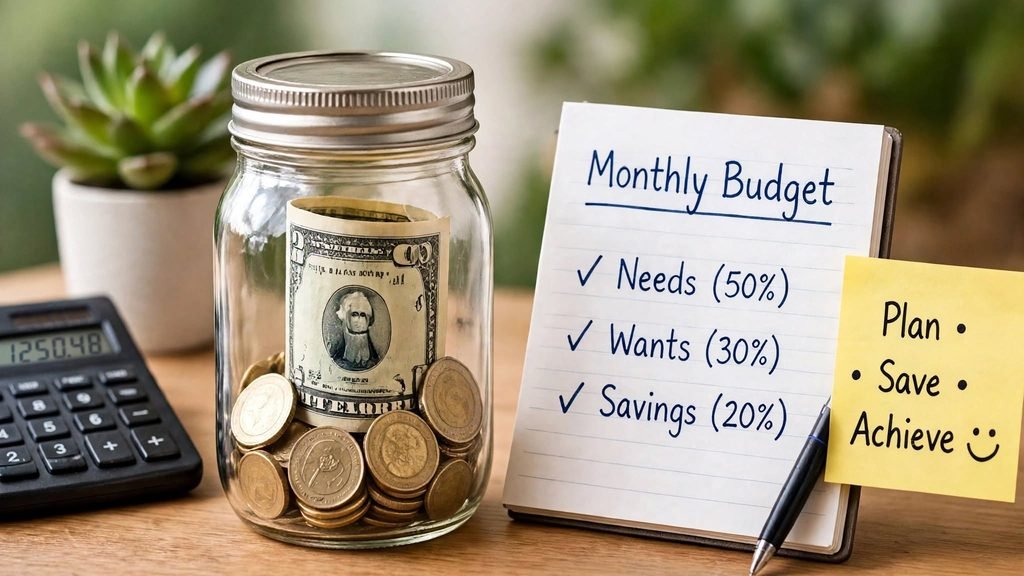
The 50/30/20 rule is a straightforward budgeting method that divides your take-home income into three categories:
- 50% for needs: Housing, groceries, utilities, transportation, and other essential expenses.
- 30% for wants: Dining out, entertainment, shopping, and other nonessential purchases.
- 20% for savings and debt repayment: Emergency savings, financial goals, and additional debt payments.
For example, if your monthly take-home income is $3,000, your budget would look like this:
| Category | Percentage | Monthly amount |
|---|---|---|
| Needs | 50% | $1,500 |
| Wants | 30% | $900 |
| Savings and extra debt payments | 20% | $600 |
| Total | 100% | $3,000 |
This is one of the most popular best budgeting methods for beginners because it is simple to follow.
Pros and cons
The main advantage of this method is its simplicity. You can organize your money without tracking every purchase in detail.
However, the suggested percentages may not work for everyone. If your rent, childcare, or transportation costs are high, your essential expenses may exceed 50% of your income.
Best for: Beginners who want a simple starting point and have relatively predictable income.
You can also use our Monthly Budget Calculator to estimate how your income could be divided between needs, wants, and savings.
Zero-Based Budgeting
Zero-based budgeting is one of the best budgeting methods for beginners who want detailed control over every dollar. You assign money to expenses, savings, and debt payments until your planned income minus your planned allocations equals zero.
This does not mean spending all your money. Savings and emergency fund contributions can also be included in your plan.
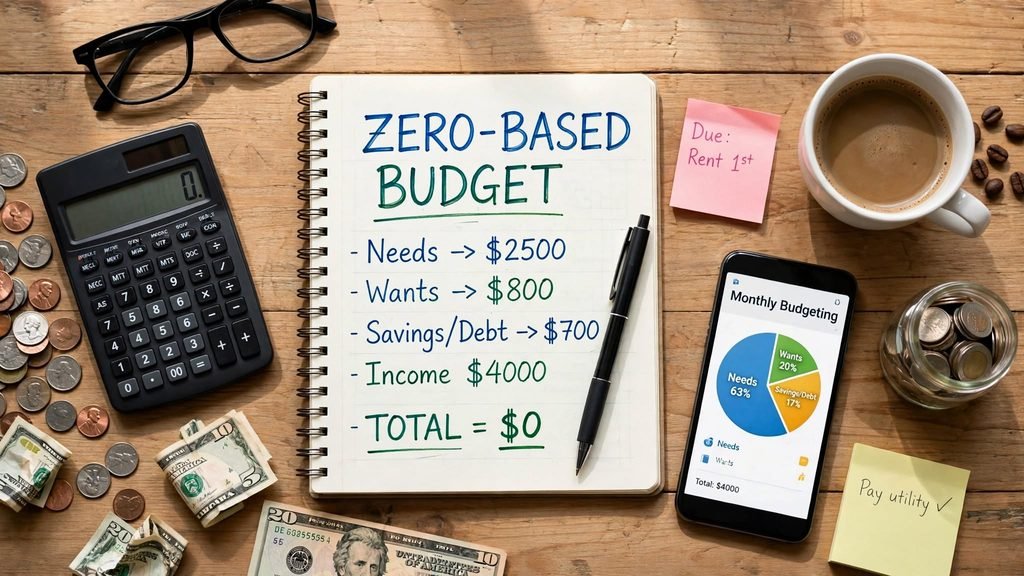
For example, if you bring home $3,000 per month, you might allocate:
- Housing and utilities: $1,200
- Groceries and household essentials: $400
- Transportation: $250
- Insurance and healthcare: $200
- Debt payments: $250
- Savings: $400
- Personal spending: $300
Total allocated: $3,000
Every dollar has a job, so you have a clearer picture of where your money is expected to go.
Pros and cons
Zero-based budgeting offers detailed control and can help you identify unnecessary expenses. It may also be useful when you are working toward a specific savings goal or paying down debt.
The main drawback is the time required to plan and review your spending. If your expenses change frequently, you may need to adjust your budget throughout the month.
Best for: People who want greater control over their money and are willing to track expenses regularly.
The Envelope Budgeting Method
The envelope budgeting method is one of the best budgeting methods for beginners who struggle with overspending. It helps you control spending by assigning a fixed amount to each category.
Traditionally, people put cash into separate envelopes for groceries, transportation, dining out, and other expenses. Once an envelope is empty, they stop spending in that category until the next budgeting period.
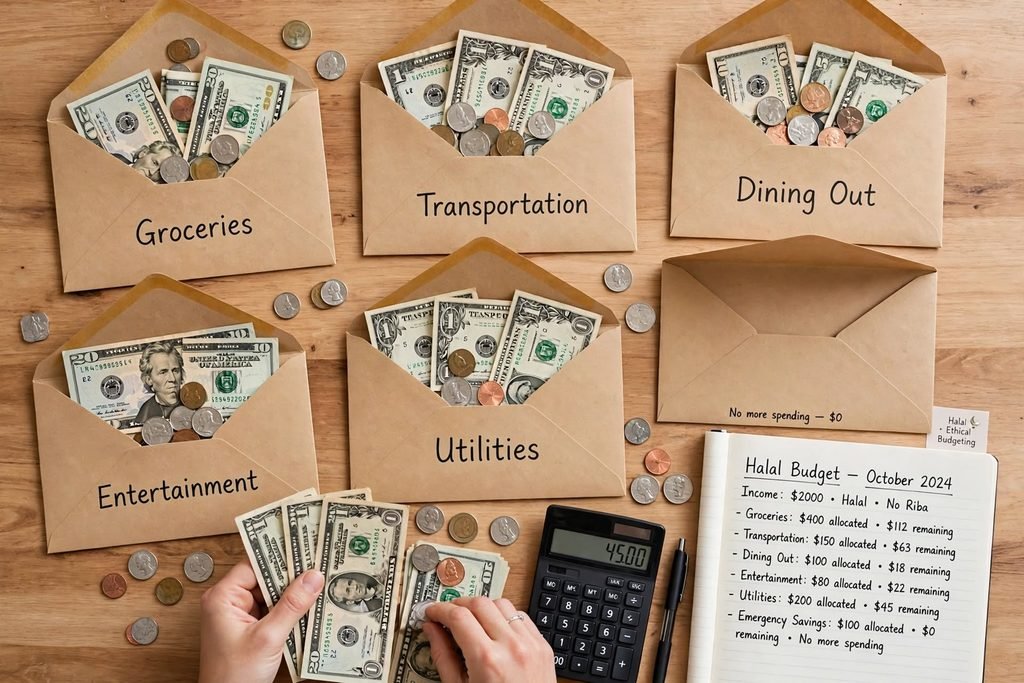
For example, you might set aside $350 for groceries and $100 for dining out each month. Keeping these amounts separate makes it easier to see how much you have left to spend.
You can also use digital budgeting tools, separate accounts, or spending categories in a spreadsheet instead of physical envelopes.
Pros and cons
This method makes spending limits easy to understand and can help reduce impulse purchases.
However, using cash for every category may be inconvenient, especially when you pay bills or shop online. Some expenses, such as rent and insurance, are also better managed through regular bill payments.
Best for: People who struggle with overspending in specific categories and prefer clear spending limits.
The Pay-Yourself-First Method
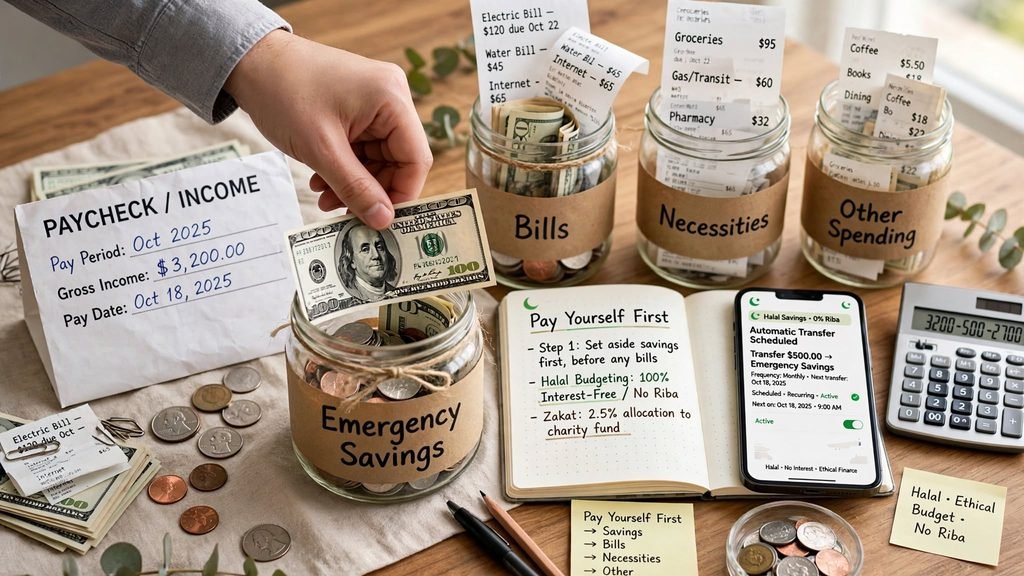
Among the best budgeting methods for beginners, the pay-yourself-first method helps you build savings automatically. With this approach, you set aside money for savings before spending on nonessential purchases.
For example, you might transfer $100 into an emergency savings account as soon as your paycheck arrives. You then use the remaining money to cover bills, necessities, and other spending.
You can start with a small amount and increase it when your financial situation improves. Automatic transfers may make the habit easier to maintain.
Pros and cons
The main benefit is that saving becomes a priority rather than something you do only when money is left over.
However, you should make sure you can still cover essential bills and avoid overdrafts. If your income is limited or irregular, a smaller transfer may be more appropriate.
Best for: People who want to build savings consistently without tracking every purchase.
For additional guidance, see the Consumer Financial Protection Bureau’s budgeting advice.
The 80/20 Budget Rule
The 80/20 rule is another of the best budgeting methods for beginners. You generally set aside 20% of your take-home income for savings and use the remaining 80% for expenses.
Unlike the 50/30/20 method, this approach does not require you to divide the remaining money into needs and wants.
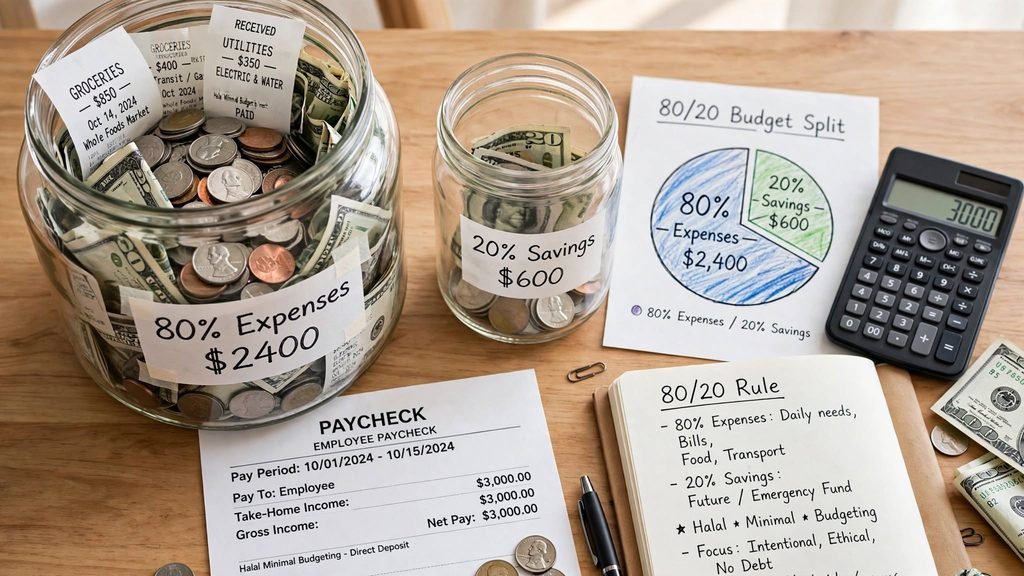
For example, if your monthly take-home income is $3,000, you would aim to save $600 and use the other $2,400 for bills, groceries, transportation, and personal spending. You can adjust the percentages if saving 20% is not realistic for your current budget.
Pros and cons
The method is easy to follow and encourages regular saving. However, it provides less detail about where your money goes, which may make it harder to identify spending problems.
Best for: People who want a simple savings-focused budget and can comfortably cover their essential expenses.
How to Choose the Best Budgeting Methods for Beginners
There is no single winner among the best budgeting methods for beginners. Your choice should depend on your income, expenses, financial goals, and how much time you want to spend managing your money.
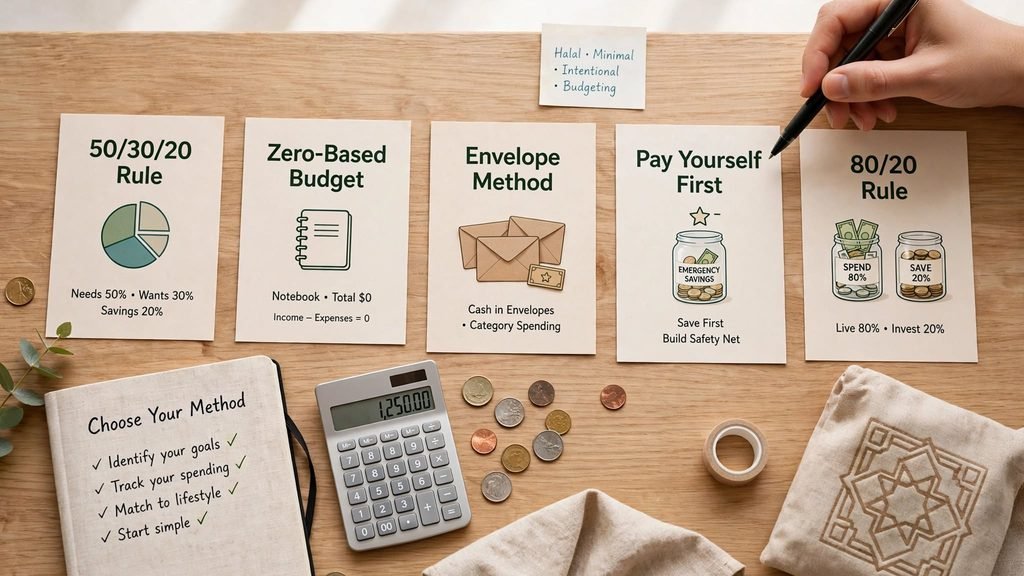
Consider these starting points:
- Choose the 50/30/20 rule if you want a simple structure for dividing your income.
- Choose zero-based budgeting if you want to plan where every dollar goes.
- Choose the envelope method if you need clearer limits for everyday spending.
- Choose pay-yourself-first if building savings is your main priority.
- Choose the 80/20 rule if you prefer a simple approach with fewer categories.
You can also combine methods. For example, you might use the 50/30/20 rule to plan your overall budget and the envelope method to control grocery and entertainment spending.
The goal is not to follow a particular rule perfectly. It is to find a system you can maintain consistently.
What If the Recommended Percentages Do Not Fit Your Income?
Even when you study the best budgeting methods for beginners, budgeting guidelines are useful starting points, but they do not reflect everyone’s circumstances.
If housing, groceries, transportation, and other essentials already take up most of your income, setting aside 20% for savings may not be realistic right now.
Start by covering essential bills, planning for irregular expenses, and identifying any spending you can reasonably adjust. Even a small amount saved regularly can help you work toward your financial goals.
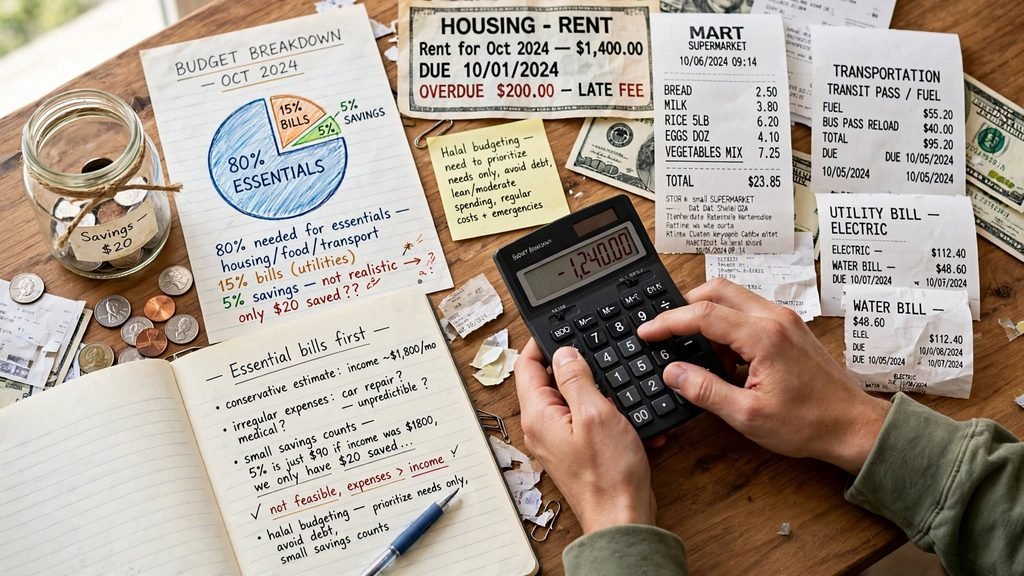
If your income varies from month to month, consider using a conservative estimate based on your typical earnings. Plan essential expenses first and adjust discretionary spending when your income is lower.
For more practical advice, read our guide on how to create a monthly budget.
How to Get Started With Your First Budget
Once you have chosen a method, keep your first budget simple.
- Calculate your take-home income. Use the amount you actually receive after taxes and payroll deductions.
- List your regular expenses. Include housing, utilities, groceries, transportation, insurance, and debt payments.
- Choose your budgeting method. Start with one system rather than trying several at once.
- Set a savings goal. Choose an amount that fits your current finances.
- Track your spending. Compare your actual expenses with your plan.
- Review and adjust. Update your budget when your income, bills, or priorities change.
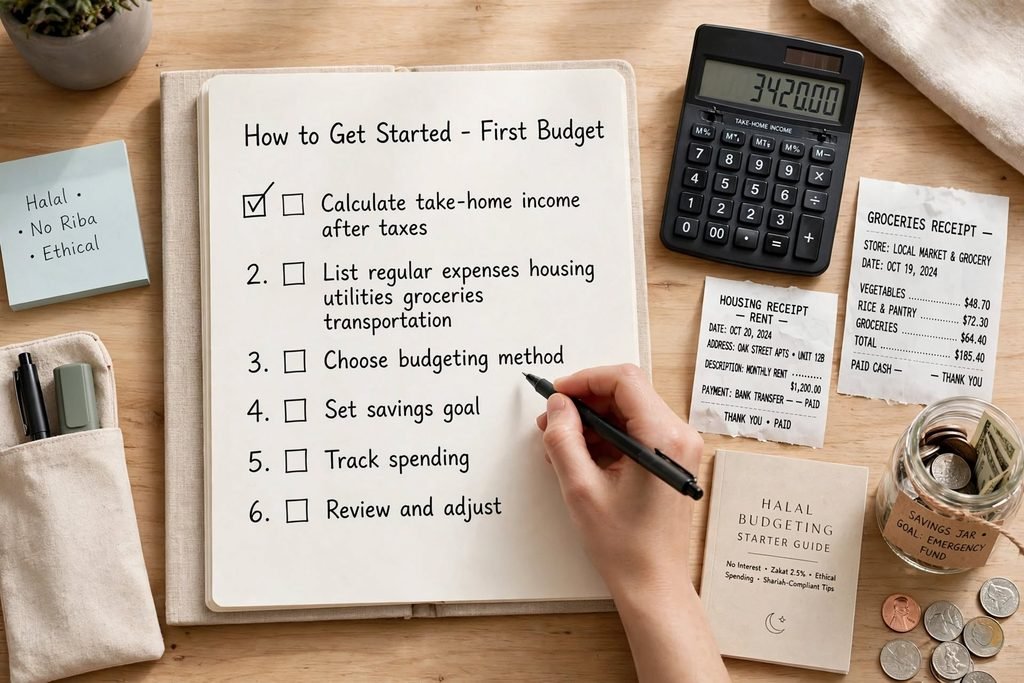
You can use the free Consumer.gov budget worksheet to organize your income and expenses.
If you are working toward a specific savings target, our Savings Goal Calculator can help you estimate how much you may need to save regularly.
Grocery Budget Tools & Helpful Guides
You can also use these free tools on AffordablyUSA to put your plan into practice:
Organize your income, needs, wants, and savings.
Estimate how much to save regularly to reach a target.
Plan food spending based on your household and shopping habits.
For more practical guidance, explore these related articles in the AffordablyUSA Budget & Money-Saving section:
Frequently Asked Questions
The 50/30/20 rule is a useful starting point because it divides take-home income into three simple categories. However, zero-based budgeting or the envelope method may be more suitable if you need closer control over spending.
It may be difficult to follow when essential expenses consume most of your income. You can adjust the percentages to reflect your actual costs and increase your savings contribution when your budget allows.
The 50/30/20 rule divides income into three broad categories. Zero-based budgeting assigns a specific purpose to every dollar, including bills, savings, and discretionary spending.
Yes. You can use a spreadsheet, budgeting app, or separate spending accounts to set limits for different categories without carrying physical cash.
The appropriate amount depends on your income, expenses, debt, and goals. Although 20% is a common guideline, starting with a smaller amount may be more realistic if your budget is tight.
Yes. You might use the 50/30/20 rule for your overall plan and the envelope method for categories where you tend to overspend. Choose a combination that remains easy to manage.
Review your spending regularly and update your plan at least once a month. You may need to make adjustments sooner if your income or expenses change significantly.